Understand the insurance position.
Review the policy, valuation provisions and the insurer’s response in the context of your loss.

FLORIDA PUBLIC INSURANCE ADJUSTING
Fine art damage can change more than an object’s appearance. Julio Ortega helps policyholders bring the insurance, the evidence, and the effect on value into focus.
JULIO C. ORTEGA · FLORIDA PUBLIC ADJUSTER · LICENSE E157479
If a painting, sculpture, or other work in your collection has been damaged, you may be facing a fine art insurance claim.
Before you accept a settlement, let's make sure the claim addresses the whole covered loss.
I'm Julio Ortega, a Florida public insurance adjuster with Active Claim Adjusters. I represent you, the policyholder.
A repair estimate may be only part of the picture.
When fine art is damaged, there can be more at stake than a visible tear, stain, or crack. Even after careful conservation, the artwork's condition history can affect its market value.
That is why I look at three connected questions.
What happened to the artwork?
What does the evidence say about its value?
And what does your policy actually cover?
A conservator evaluates the physical condition and treatment options. A qualified art appraiser addresses the relevant value questions.
My role is to bring that evidence and the policy terms together. I present your claim and communicate with the insurance company on your behalf.
Where specialist input is needed, we discuss the appropriate professionals. You do not have to connect every part of the claim yourself.
Imagine a painting damaged by water. A conservation proposal may explain the treatment it needs.
But will the artwork still have a supported loss in value afterward?
If your policy covers that loss, it deserves its own analysis.
There is no automatic percentage. Coverage and evidence matter.
The point is to examine the whole covered loss before an incomplete picture becomes the basis for a settlement.
Whether you own one important work, manage a private collection, or operate a gallery, I can review where your claim stands.
That includes damage at a property, in storage, or during transportation, where the applicable policy provides coverage.
I can also review a claim already underway, or a settlement offer you want to understand.
Your insurer has a claims professional. You can have a licensed public adjuster representing your interests.
Call me, Julio Ortega, at seven eight six, five four seven, six seven five one.
Or visit Art Damage Claims dot com.
Let's talk about your artwork, your loss, and how I can help.
Active Claim Adjusters LLC
Florida license E157479
LOOK BEYOND THE SURFACE
A treatment proposal can describe how to address physical damage. It may not answer every question about the financial loss—or what your insurance should respond to.
Julio’s role is to represent your interests and bring those questions together in a clear, supported claim.
WHAT CHANGED IN THE OBJECT?
The medium, location and extent of the damage matter. A conservator’s examination and treatment findings can help explain what happened to the work and what careful treatment may achieve.
Paintings · Sculpture · Works on paper · Fine-art photography
The claim depends on the actual policy. Restoration and residual loss in value are separate questions; neither is an automatic entitlement.
 ILLUSTRATIVE CONSERVATION SCENE
WHEN CONSERVATION IS ONLY PART OF THE ANSWER
Damage and treatment may affect how an artwork is viewed in the market. Where your policy provides for it, a supported claim may need to address both conservation costs and any remaining loss in value.
That takes object-specific evidence. There is no responsible, universal percentage for every damaged work.
Explore loss in value ↗ONE IMPORTANT WORK. AN ENTIRE COLLECTION.
The claim should reflect how the work is owned, insured, held and used—not a generic contents estimate.
Individual paintings, sculptures and collections held in a home, private space or storage.
Discuss a collection loss ↗02 / GALLERIES & DEALERSReview the ownership, custody and insurance questions behind damaged gallery works.
Explore gallery claims ↗03 / BUSINESS COLLECTIONSFine art displayed or held by businesses, offices, hospitality properties and institutions.
Review business-owned art ↗FROM THE WALL TO THE CRATE
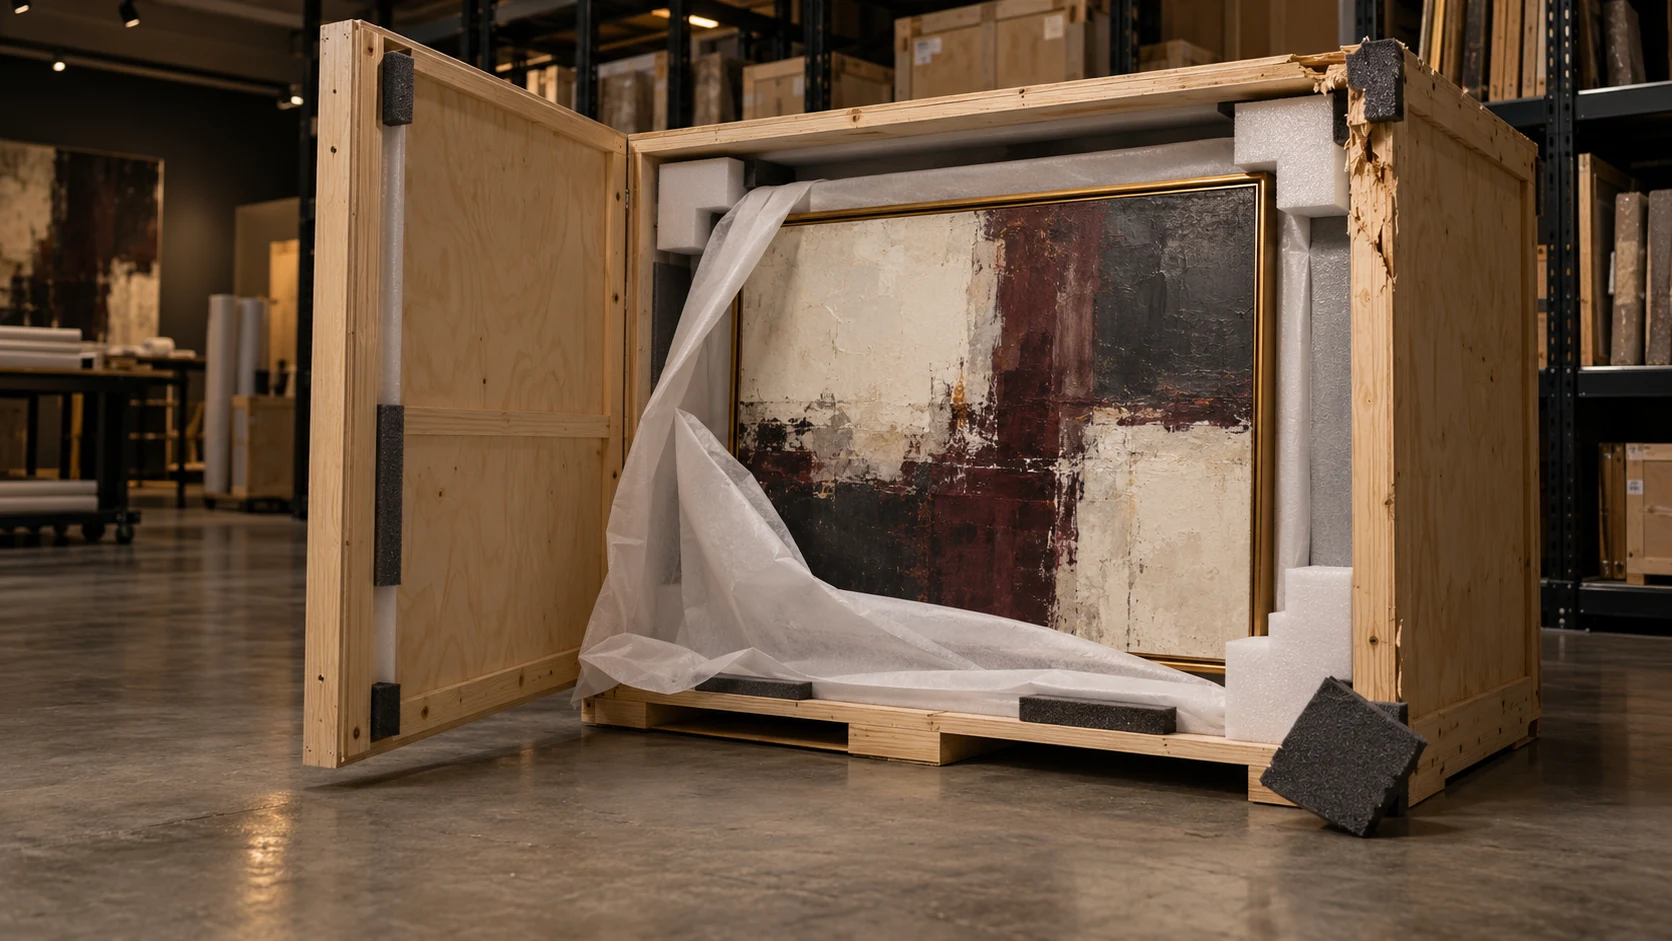
Water and smoke. Accidental impact. Damage in handling, transportation or storage. Each event presents its own coverage and valuation questions.
Examples are loss situations to review, not a statement that any particular policy covers them.
A PROFESSIONAL REPRESENTING YOUR INTERESTS
Your insurer has a claims professional. You can have a licensed public adjuster working for you.
Meet Julio Ortega ↗Review the policy, valuation provisions and the insurer’s response in the context of your loss.
Bring condition, treatment and appropriate appraisal findings into the claim. Discuss outside expertise when needed and agreed.
Organize the supported loss, communicate with the insurance company and review its response with you.
BEFORE WE SPEAK
It can, but not every restoration produces measurable diminution. The type of work, damage, treatment, market evidence and policy terms all matter. Where covered and supported, residual loss in value deserves a separate analysis.
Julio’s role is public insurance adjusting for the policyholder. A qualified art appraiser addresses value; a conservator addresses physical condition and treatment. Those are distinct professional roles. Appropriate outside input can be discussed within the agreed scope.
Yes. A review can consider what has been presented, the insurer’s reasoning and whether relevant evidence or policy questions remain unresolved. Services depend on the circumstances and an accepted agreement.
Not necessarily. Agreed value, blanket coverage, partial-loss provisions, limits and endorsements can work differently. The actual terms determine how the loss is measured.
Yes. Begin by identifying who owns the work, who held it when damaged, the relevant agreements and which policy may respond. A gallery’s insurance and the owner’s coverage are not automatically interchangeable.
The scope, fees and terms are addressed in an accepted written agreement, subject to Florida requirements. Any outside specialist services and costs should be discussed and appropriately authorized. A website inquiry alone does not create representation.
TALK TO JULIO ABOUT YOUR ART CLAIM
A damaged work. An unanswered question.
An offer you want to understand.
PREFER TO WRITE?
Prepare a short introduction, then send it to Julio from your own email app.
Nothing has been sent. Open the draft, review it in your email app, then send it when ready.
Open email draft ↗